
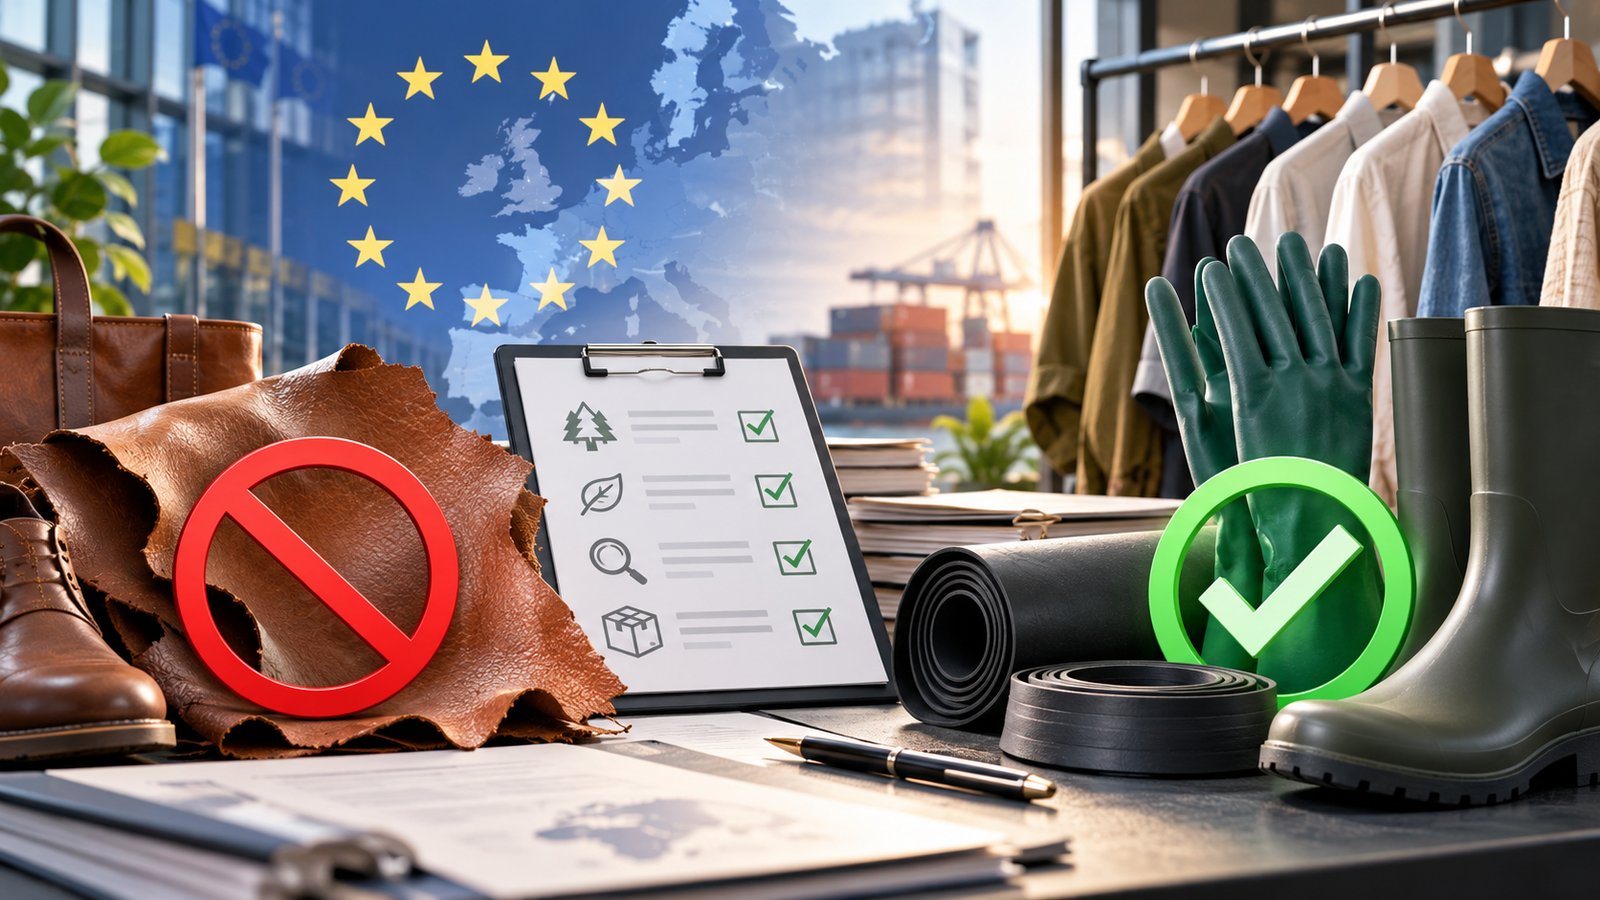
Most finished clothing and footwear is not directly listed in Annex I of the EU Deforestation Regulation (EUDR). But some materials and rubber apparel products can be covered, depending on their customs classification. That distinction became more important after a September 2026 amendment removed cattle hides and leather from the regulated product list while retaining certain natural-rubber products.
For fashion buyers, the right question is not simply “Does this contain leather, wood or rubber?” It is: Which product is being placed on the EU market or exported, under which CN code, and is that code currently in Annex I? This guide reflects the legal position checked on 19 October 2026.
Start with Annex I, not a list of materials
Regulation (EU) 2023/1115, as consolidated on 18 September 2026, covers specified products linked to seven commodities: cattle, cocoa, coffee, oil palm, rubber, soya and wood. It does not automatically regulate every product containing one of those materials. The actual product description and Combined Nomenclature (CN) code in Annex I determine whether an item is covered.
For example, a finished leather jacket classified in Chapter 42 or ordinary footwear in Chapter 64 does not become an Annex I product merely because it contains leather or rubber. Conversely, the annex expressly lists certain articles of vulcanised rubber under ex 4015, including rubber apparel and gloves. The prefix ex matters: the entry is limited to the products described, rather than every good under a heading.
What changed for leather on 18 September 2026?
Commission Delegated Regulation (EU) 2026/2102 was published in the Official Journal on 17 September 2026 and entered into force the following day. It deleted three cattle-derived product entries from Annex I: ex 4101 (raw hides and skins), ex 4104 (tanned or crust hides) and ex 4107 (further-prepared leather). These deletions are in force now; they are not merely proposals.
That does not remove cattle meat or every cattle-derived product from the regulation. It also does not mean that finished leather jackets or shoes were newly exempted: those finished goods were not listed in Annex I in the first place. A procurement team relying on an older 2025 checklist could easily reach the wrong conclusion, especially if the checklist treats “leather” as a single regulatory category.
Which fashion-related goods still need screening?
| Product or input | Annex I position as checked in October 2026 | What a buyer should verify |
|---|---|---|
| Finished textile clothing (typical Chapters 61–62) | Not listed simply as clothing | Actual CN code and whether another separately traded input is listed |
| Finished leather apparel and ordinary footwear (Chapters 42 and 64) | Not listed merely because of leather or rubber content | Product classification; do not transfer raw-material obligations to an unlisted finished article |
| Cattle hides and leather formerly at ex 4101, 4104, ex 4107 | Deleted from Annex I by Regulation 2026/2102 | Current consolidated annex rather than a pre-September checklist |
| Natural rubber in specified primary or intermediate forms | Several Chapter 40 entries remain listed | Precise CN heading and whether the material is covered natural rubber |
| Specified vulcanised-rubber apparel and gloves (ex 4015) | Still listed, with exclusions including used goods | Material, classification and scope of the listed description |
| Wood pulp and certain paper products | Specified Chapter 47–48 entries remain listed | Whether the traded input is listed; do not equate all regenerated cellulose clothing with pulp |
The amended annex clarifies that the rubber commodity concerns Hevea brasiliensis, not synthetic rubber or every natural gum. It also expressly excludes bamboo and rattan from its wood definition. These details can change a classification analysis, but they do not replace checking the actual traded product.
Does a viscose or lyocell garment fall within the EUDR?
A fibre’s forest origin is not enough to make the finished garment a regulated product. Wood pulp can appear under a listed heading; a finished garment made from regenerated cellulose typically has a different tariff classification that is not listed as apparel in Annex I. Buyers should separately review the import or export of any in-scope pulp or paper inputs, and avoid describing a fabric-level sustainability claim as proof of EUDR compliance.
This is also why supply-chain mapping and product-specific regulatory screening are different exercises. A supplier map tells you who handles a material; the annex tells you which legally classified product triggers the regulation.
Who has obligations, and when?
For covered products, obligations depend on the business’s role in placing the product on the EU market, making it available, or exporting it. The amended rules distinguish operators from downstream operators and traders. An in-scope operator may need to assemble due-diligence evidence and submit a statement through the EU system; downstream parties’ obligations differ. Do not assume that every overseas factory files the EU statement itself.
The European Commission’s current implementation page states the principal application dates: 30 December 2026 for large and medium operators, and 30 June 2027 for micro and small operators, with a specific earlier date for small operators already covered by the EU Timber Regulation. Newly added product entries under the 2026 delegated act, such as certain palm derivatives and soluble coffee, have a separate 30 December 2027 application date. None of these dates brings a product into scope if it is not in Annex I.
A five-step sourcing check before making a compliance claim
- Identify the traded product. Is the company importing a finished garment, a roll of material, a rubber glove, pulp, or another input?
- Confirm the CN classification. Record the actual code and a defensible description. An invoice’s generic “fashion accessories” label is not enough.
- Read the current Annex I entry. Include all ex qualifications and exclusions. Use the consolidated September 2026 version rather than a historic PDF.
- Determine the business role and date. Identify who first places the listed product on the EU market, who trades it downstream, and which application date applies.
- Document the result and review triggers. Save the code, source, date, classification reasoning and responsible reviewer; revisit the decision when a material, supplier, product code or regulation changes.
For in-scope supply chains, build records that connect the relevant product to its supporting evidence. A general supplier declaration is not a substitute for traceable transaction records; see our explainer on apparel traceability events and records.
Sources and editorial note
Primary sources reviewed on 19 October 2026: consolidated EUDR text and Annex I (18 September 2026); Delegated Regulation (EU) 2026/2102; and the European Commission’s implementation overview. This is a product-scope guide, not legal advice or an assessment that any individual supply chain is deforestation-free. Check the current law and obtain product-specific classification advice where needed.
